Pallas Preference Equity - Doggett Street, Teneriffe
Top-up Coupon Rate
17.5% p.a.
Minimum
$50,000
Term
To Jul 2029
Executive Summary
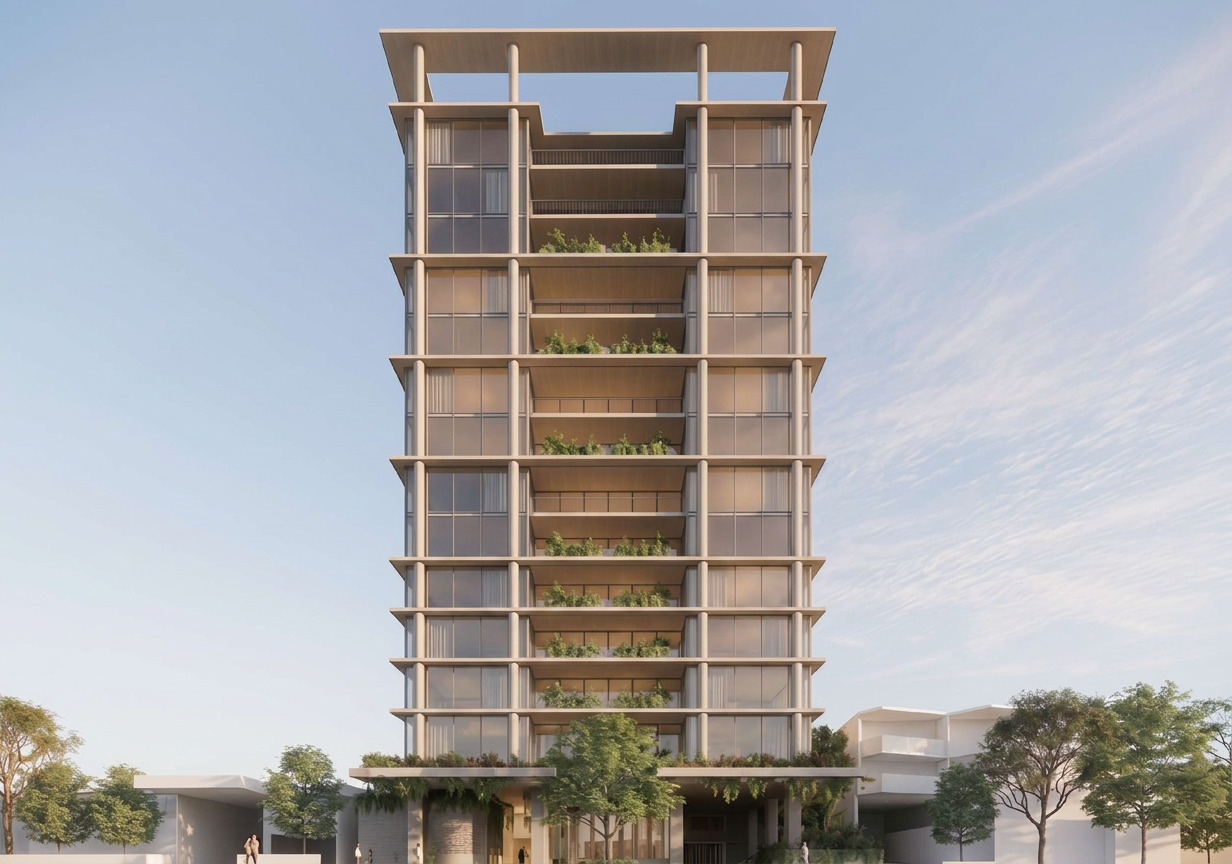
The Doggett Street Capital Trust offers Preference Units that fund, through an unsecured Trust Loan to the Developer, a proposed 15 storey building of 92 luxury residences and a ground floor retail lot at 49 Doggett Street, Teneriffe QLD. Preference Units issued after the date of the Information Memorandum carry a Top-up Coupon of 17.5% per year or part thereof, without compounding, paid on the Redemption Date, unless otherwise determined by the Issuer prior to issue. Repayment of the Subscribed Amount upon redemption is guaranteed jointly and severally by the Guarantors. Payment of the Coupon, if any, and the Top-up Coupon is not guaranteed by the Guarantors. All Preference Units must be redeemed by the Maturity Date of 31 July 2029, which the Issuer Trustee may defer by up to 12 months if the Project is delayed. An investment in the Issuer is speculative and subject to investment risk, including possible delays in repayment and loss of income and principal invested. The offer is arranged by Pallas Capital and is open to wholesale clients and sophisticated investors only, with a minimum investment of $50,000.
Investment Highlights
- Top-up Coupon of 17.5% per year or part thereof, without compounding, calculated on the Subscribed Amount and paid on the Redemption Date. This rate applies to Preference Units issued after the date of the Information Memorandum unless otherwise determined by the Issuer prior to issue. Payment is not guaranteed by the Guarantors and depends on the Issuer Trustee obtaining further funding.
- Coupon payments during the Project depend on the ability of the Issuer Trustee to obtain further funding, mainly by issuing further Preference Units. Redemption depends primarily on that same source during the Project, and on payments by the Developer under the Trust Loan at its conclusion.
- Repayment of the Subscribed Amount upon redemption is unconditionally and jointly and severally guaranteed by the Guarantors, the family trusts associated with Dan Gallen, Charles Mellick and Patrick Keenan, which are also the ultimate beneficial owners of a majority of the Pallas Group. Their financial strength, and their ability to generate liquid assets when required, will vary over time. The Coupon, if any, and the Top-up Coupon are not guaranteed by them.
- The proposed building is expected to comprise 92 luxury residences, a 133 sqm ground floor retail lot and basement parking for 239 cars, with approximately 14,205 sqm of net saleable area, designed by architects Fraser and Partners.
- The Developer signed a contract in November 2025 to purchase the 2,386 sqm property at 49 Doggett Street, Teneriffe QLD for $31.5 million, and is due to settle that purchase in July 2026.
- A Charter Keck Cramer Valuation Report dated 2 February 2026 supports a completed value of approximately $334.2 million including GST on an as if complete basis, assuming the development application is approved. The Valuation Report is not prepared for mortgage purposes and no person other than the Developer may rely on it.
- At the date of the Information Memorandum the Developer had not yet obtained planning approvals, signed a fixed price contract with a builder, achieved off the plan sales of Residences or arranged the Construction Loan, and construction had not commenced.
- Generally, the less advanced the Project is, the greater the risk.
- The Developer's Feasibility Analysis indicates a Development Profit of about $42.4 million, a 16.2% return on total development costs of about $262.2 million, before payment of the Coupon, if any, and the Top-up Coupon, and a Project Profit of about $24.6 million after those coupons. Forward looking, illustrative only and not guaranteed.
- The Trust Loan is an unsecured debt of the Developer, ranking behind all secured debts including the Construction Loan and, except as stated in Section 5.2 of the Information Memorandum, ahead of all ordinary units in the Developer for distributions of income and capital, to the extent required to fund full payment of the Redemption Amount.
- In certain circumstances the Issuer Trustee may be able to obtain a mortgage ranking behind the mortgages securing the Construction Loan, and issue Second Mortgage Units ranking pari passu with the Preference Units, although that outcome is by no means guaranteed.
- Until construction commences the Issuer will not issue Preference Units with a total Subscribed Amount exceeding 85.0% of: (a) the total net realisable value of the Residences in the Developer's most recent Feasibility Analysis, minus (b) the total of monies owed by the Developer and secured on the Property. That maximum may increase to 90.0% once construction of the Building has commenced.
- All Preference Units must be redeemed by the Maturity Date of 31 July 2029, which the Issuer Trustee may defer by up to 12 months if the Project is delayed.
- Early redemption requires at least 6 months prior written notice, which cannot be given in the first 12 months after issue, so the minimum initial investment period is 18 months. It is also conditional on the Issuer Trustee having sufficient funds to make that redemption without prejudice to the conduct of the Project or to the Issuer.
- The Issuer may redeem some or all Preference Units at any time. An investment in the Issuer is illiquid.
- Pallas Group fees payable as costs of the Project include a Fortis acquisition fee of 3.5% of the adopted property valuation, an arrangement fee of 3.0% of monies subscribed, development management fees of $50,000 per month and project management fees of $16,500 per month.
- Fortis will charge a performance fee of 20% of the Development Profit, which Fortis will waive if and to the extent necessary to increase payments by the Developer under the Trust Loan and assist the Issuer to meet its obligations.
- The Arranger may charge a market standard loan establishment fee, or advisory or arrangement fee, for any loans it manages or arranges.
- These Pallas Group fees do not affect the Coupon or Top-up Coupon but do reduce the Project Profit.
- The owners of the Developer, who are the Guarantors, are also entitled to monies, as trust distributions or loans, representing increases in the value of the Property during the Project, typically paid before redemption of Preference and Ordinary Units.
- Arranged by Pallas Capital Pty Limited as authorised representative of Pallas Funds Pty Limited, holder of AFS Licence 473475, which is also the Issuer Trustee.
- The Issuer, the Arranger, Fortis, the Developer and the Guarantors are related parties.
- The Issuer is an unregistered unit trust and the offer is available only to wholesale clients and sophisticated investors under sections 761G and 761GA of the Corporations Act, with no cooling off rights.
- Minimum investment $50,000, although the Issuer may accept less in its absolute discretion.
- The Information Memorandum must be read with the Issuer Trust Deed, the Subscription Deed and the other transaction documents, which prevail over it in any inconsistency.
Source: Preference Equity, Doggett Street, Teneriffe QLD Information Memorandum (31 March 2026).
Ready to Invest?
Register your interest and our advisor will be in touch within one business day.
Licence Notice: Managed Investment Scheme (AFSL 416956)
This is general advice only. Content relating to this managed investment scheme is prepared by Figure 8 Capital Pty Ltd ABN 49 681 113 100 (operating Investing Platform), a Corporate Authorised Representative (No. 001311723) of Alpha Node Advisors Pty Ltd (ACN 154 320 000, AFSL 416956), and is available exclusively to wholesale clients and sophisticated investors within the meaning of sections 761G and 761GA of the Corporations Act 2001 (Cth). Investing Platform receives an upfront fee from the issuer on amounts invested, as well as an ongoing fee for the duration of your investment. These fees are paid by the issuer and are not charged to you directly. Read the Website Disclaimer for the full dual-licence explanation.